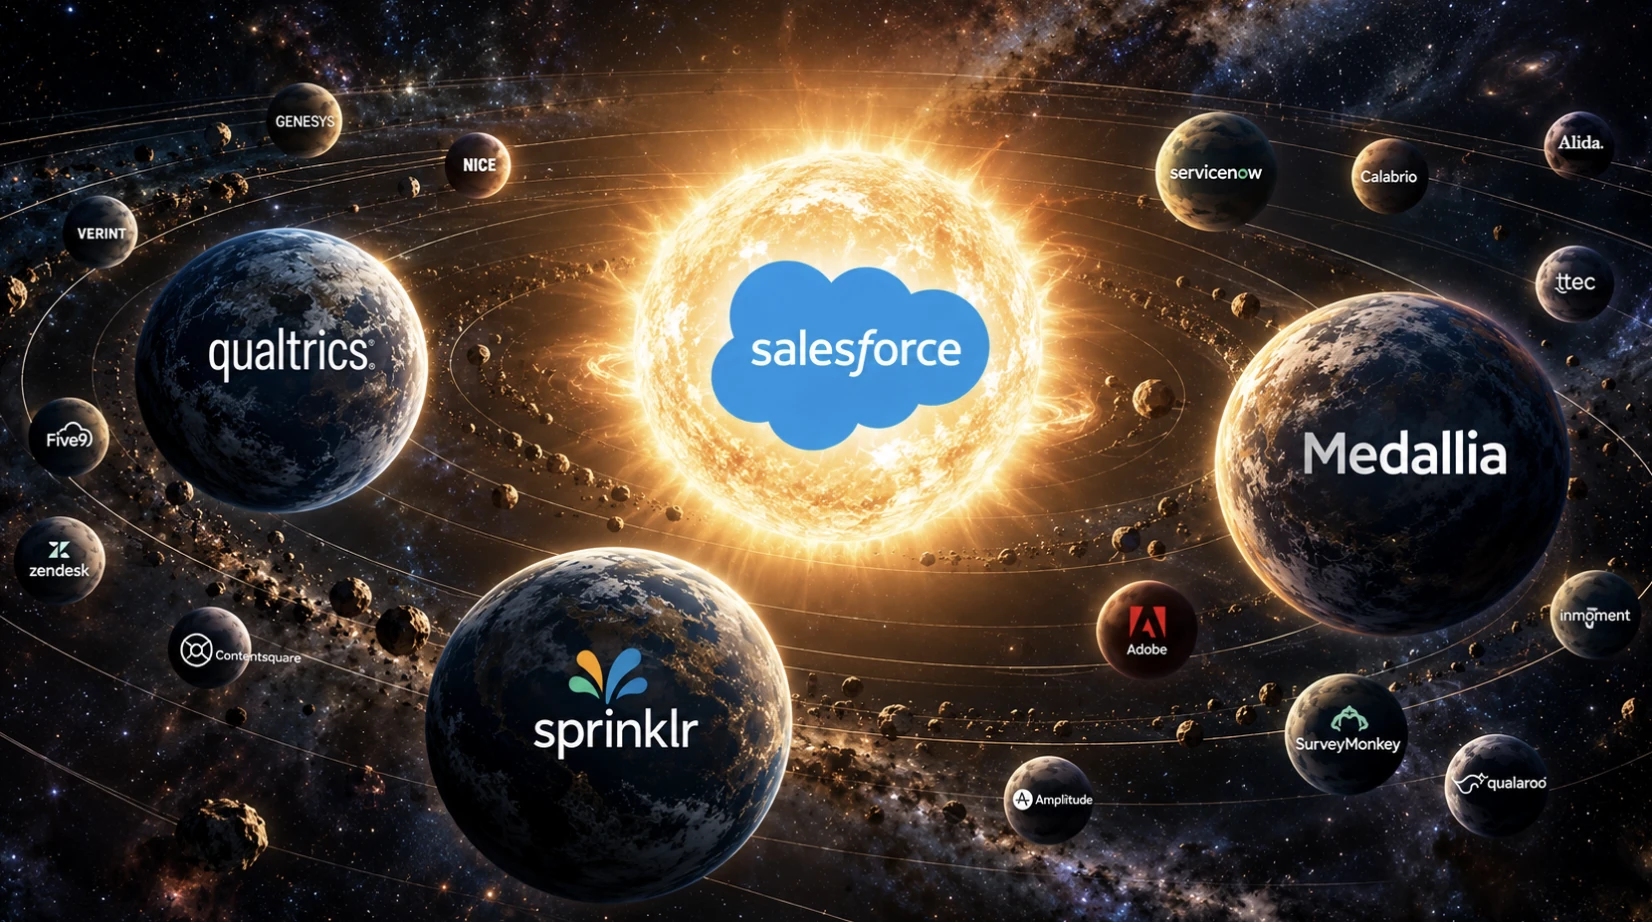
If the customer experience technology market were a solar system, Salesforce would sit somewhere near the center of it right now.
It has the scale, customer relationships, data, workflow footprint and expanding AI capabilities to exert enormous gravitational pull over almost every company selling technology to customer-facing teams.
Further out sit some of the companies that helped define customer experience software as its own market: Qualtrics, Medallia and Sprinklr. These are not small companies. They have large enterprise customer bases, hundreds of millions or billions of dollars in revenue and technology embedded inside some of the world's largest organizations.
But they also now operate in a very different universe from the one that produced their previous valuations.
Sprinklr is public, so the market tells us every day what investors are currently willing to pay for it. Medallia went private at a $6.4 billion transaction value in 2021 and has since gone through a recapitalization that transferred ownership from Thoma Bravo to its lenders. Qualtrics was acquired for approximately $12.5 billion in 2023, then completed the $6.75 billion acquisition of Press Ganey Forsta this year. The combined company now generates ~$3 billion in annualized revenue and carries roughly $6.7 billion of term debt.
Those numbers raise a lot of questions that deserve more attention across the CX technology market.
What are these companies actually worth now?
More importantly, what happens if the market no longer values mature CX software at anything close to the multiples that supported the acquisitions made earlier this decade?
The answer has implications far beyond private equity. Valuation affects how aggressively vendors can invest, what acquisitions they can make, how much flexibility management has, whether a company can remain independent and, eventually, which platforms customers may still be buying from five years from now.
Sprinklr gives us a public-market reality check
Sprinklr is the cleanest place to start because we can see its valuation.
As of late September 2026, Sprinklr has approximately $873 million in trailing revenue and a market capitalization of roughly $1.1 billion. That produces a price-to-revenue multiple of approximately 1.3x.
But putting my former Wall Street analyst hat on, I know that market capitalization is not the best number for comparing Sprinklr with heavily leveraged private companies.
An important point to highlight for readers that didn't work for a spell in the capital markets, market capitalization measures the value of the equity. Enterprise value measures the value investors place on the operating business after adjusting for cash and debt.
Sprinklr has significant cash and marketable securities. Its current enterprise value is approximately $745 million, which means the public market is valuing the operating company at only about 0.85x trailing revenue.
That is an extraordinary reset from where enterprise software traded only a few years ago. In fairness to them, they also have strong new leadership in place that are trying to evolve the business through smart tuck-ins.
Other public companies show that the market will pay considerably more for software companies with the right combination of growth, margins, competitive position and future opportunity.
NICE currently trades at approximately 2.1x enterprise value to revenue, with trailing revenue just over $3 billion. Five9 is a little above 2x. DocuSign, while not in the CX space, is another mature enterprise software company growing in the high single digits, is closer to 3.5x enterprise value to revenue.
So there is no single "CX software multiple."
The market is telling us the range can stretch from below 1x to somewhere around 3x or 4x for mature software companies, depending on what investors believe about the next several years. This range matters enormously when debt is involved.
As a former fixed income analyst at JPMC, I have to admit I never thought the knowledge would be important anymore after leaving that role to focus on customer experience.
Medallia shows what happens when debt and valuation collide
Thoma Bravo acquired Medallia in October 2021 in a transaction valued at $6.4 billion. That clearly was a very different software market.
Capital was cheaper. Growth received much higher valuations. Recurring SaaS revenue carried a premium almost by default. Investors were also willing to assume that large software companies could continue compounding growth long enough to justify aggressive acquisition prices.
By 2026, Medallia had approximately $2.8 billion of debt. You are likely aware that Bloomberg reported in May that lenders led by Blackstone were preparing to convert a large portion of that $2.8 billion loan into equity as part of a restructuring.
Medallia does not publish current revenue because it is private, so any current estimate requires some caution.
One useful datapoint came this summer when ABC Fitness announced the hiring of former Medallia Chief Client Experience Officer Jodi Searl. The announcement said she had accountability for more than $800 million in Medallia annual recurring revenue.
That does not mean Medallia's revenue is exactly $800 million. ARR and reported revenue are different measures. But it gives us a credible anchor.
For the purposes of this analysis, I use approximately $900 million in annual revenue, with the understanding that the actual number could reasonably be somewhat higher or lower.
Now consider the math.
At 1.5x revenue, Medallia would have an enterprise value of approximately $1.35 billion. The debt was approximately $2.8 billion.
At 2x revenue, Medallia would be worth about $1.8 billion. At 2.5x, approximately $2.25 billion. At 3x, approximately $2.7 billion.
The business needs to be valued at roughly 3.1x annual revenue simply for enterprise value to equal the $2.8 billion debt balance.
And that only gets the company to the point where lenders are covered. It does not recreate the equity value Thoma Bravo paid for in 2021. This is the important part of the Medallia story.
The company did not need to fail for the equity to disappear.
Medallia could remain a large software company, retain major enterprise customers, employ thousands of people and generate close to $1 billion in revenue while still being worth less than the amount owed to lenders. That is what leverage does.
When the value of the business falls below the debt, the lenders economically own the company whether the legal restructuring happens immediately or later. In Medallia's case, it eventually happened.
In June, Medallia announced an agreement that would transfer ownership from Thoma Bravo to an investor group led by Blackstone, Apollo and FS KKR. The transaction closed in August, 2026.
Medallia said the recapitalization "significantly reduced" its outstanding debt and provided another $150 million in capital. The exact amount of remaining debt has not been disclosed publicly. That last point is important because the Medallia story has now changed.
The old $2.8 billion debt structure should no longer be used to judge the value of the company today. A meaningful portion of that debt was converted into ownership. The lenders became the equity holders, so they reset the capital structure.
The Medallia reset may actually create a healthier business
There is a tendency to view restructurings as evidence that the underlying company is broken. That conclusion should not automatically follow.
Medallia's capital structure was broken relative to what the market was willing to pay for the business. Fixing that structure may give management more room to operate.
The new ownership group has already put $150 million into the company. Medallia says that funding supports a broader $500 million commitment to innovation, including AI.
The new owners also have a very different economic starting point from Thoma Bravo. They do not need Medallia to return to a $6.4 billion valuation simply to make the transaction worthwhile.
Suppose Medallia eventually reaches $1 billion to $1.1 billion in revenue. At 2.5x revenue, that would imply an enterprise value somewhere around $2.5 billion to $2.75 billion. At 3x, approximately $3 billion to $3.3 billion. At 3.5x, roughly $3.5 billion to $3.85 billion.
Without knowing the new debt balance and the effective basis at which the lenders converted debt into equity, we can't calculate what return those values would produce.
But the new owners have something Thoma Bravo eventually lost: flexibility. My base scenario for Medallia is therefore relatively straightforward. I think the new owners hold the company for several years.
Management focuses on retaining large enterprise customers, improving growth, expanding margins and moving Medallia's value proposition further into AI-driven operational action rather than remaining primarily associated with traditional customer feedback management. They're already trying to do this.
If that works, I think Medallia eventually exits somewhere in the $2.5 billion to $3.5 billion range, potentially higher if growth materially accelerates. I would also place a strategic acquisition or another sponsor transaction ahead of an IPO as the most plausible path.
The business could IPO again, but it does not need to. A strategic buyer that values Medallia's enterprise relationships, customer data, workflow integration, and installed technology could justify a higher valuation than public markets would give a standalone CX software company. I think the recap makes that type of outcome more possible.
Qualtrics is a much larger version of the same valuation test
Qualtrics is different from Medallia in several important ways. First, it is larger. Its retention metrics are strong and margins are improving.
Moreover, its acquisition of Press Ganey Forsta adds an unusually valuable healthcare data asset and deeper industry expertise.
And according to Fitch, the combined business now generates more than $2.9 billion in annualized revenue. Approximately 85% of Qualtrics revenue is subscription-based, gross retention is in the high-80% range (yes, could be better) and net retention remains above 100%. Fitch expects normalized revenue growth in the high single digits and EBITDA margins to reach the mid-to-high 30% range.
Those are the characteristics of a substantial enterprise software company. But Qualtrics also has a substantial debt load.
Fitch reports a $1.4 billion secured term loan due in 2030 and a new $5.3 billion secured term loan due in 2033. That is $6.7 billion of term debt.
Qualtrics also has a $500 million revolving credit facility, although that should not simply be added to debt unless drawn. So using a round $3 billion current revenue figure, here is what the valuation looks like:
| EV / Revenue | Enterprise Value | Value Above $6.7B Term Debt* |
|---|---|---|
| 1.0x | $3.0B | ($3.7B) |
| 1.5x | $4.5B | ($2.2B) |
| 2.0x | $6.0B | ($0.7B) |
| 2.5x | $7.5B | $0.8B |
| 3.0x | $9.0B | $2.3B |
| 3.5x | $10.5B | $3.8B |
| 4.0x | $12.0B | $5.3B |
Illustrative analysis before cash, other liabilities, transaction costs and other claims.
The first conclusion is obvious. At Sprinklr's current sub-1x EV/revenue valuation, Qualtrics' capital structure would be deeply underwater. Even at 1.5x revenue, the business would be worth approximately $2.2 billion less than its term debt. At 2x, the debt would still exceed enterprise value.
Qualtrics needs an enterprise value of roughly 2.2x to 2.3x current annualized revenue merely for the $6.7 billion of term debt to be covered.
Only above that point does meaningful equity value begin to emerge. That does not mean Qualtrics is worth 2.3x. It tells us where the capital structure begins to work.
The harder number is not $6.7 billion. It is $12.5 billion.
Silver Lake and CPP Investments acquired Qualtrics in 2023 in a deal that valued its equity at approximately $12.5 billion.
Qualtrics subsequently acquired Press Ganey Forsta for another $6.75 billion using a combination of debt, equity and cash.
Now consider what it would take simply to recreate $12.5 billion of Qualtrics equity value today.
With $6.7 billion of term debt sitting ahead of the equity, the company would need an enterprise value of approximately $19.2 billion. Against $3 billion of current revenue, that is roughly 6.4x revenue.
The comparison is imperfect because the company today includes Press Ganey Forsta and the capital invested in the combined business has changed. But the calculation illustrates how dramatically the valuation hurdle has moved.
As a reminder:
Sprinklr is below 1x EV/revenue.
NICE is around 2x.
Five9 is just over 2x.
DocuSign is around 3.5x.
For the combined Qualtrics business to support an enterprise value approaching $19 billion at current revenue, investors would need to view it as something considerably more valuable than a mature customer experience software platform.
Which brings us directly to the point: Artificial Intelligence.
AI could compress the multiple or create the reason for a premium
AI creates two opposing forces for companies like Qualtrics and Medallia.
The first is commoditization. Generative AI can already summarize interviews, categorize open-text feedback, analyze calls, create surveys, find themes in qualitative research and generate recommended actions. We also have to add in new entrants like TypeSafe AI's System One model, Jev.
Capabilities that once required specialized software increasingly appear inside CRM systems, contact-center platforms, analytics products and general-purpose AI tools.
That creates a serious question for the traditional experience management category.
For example, CXOs should be asking, "How much of what customers historically paid a standalone CX platform to do will remain differentiated?"
Just take generative AI as an example. Fitch describes it as a medium-term technology disruption risk for Qualtrics. It also points to Qualtrics' deep workflow integration, switching costs, proprietary benchmarking data, and industry expertise as meaningful defenses.
And here's the second force. AI makes proprietary data more valuable when the data improves the quality, context, and accuracy of what AI can do.
This helps explain why Press Ganey may ultimately prove strategically important. Qualtrics did not spend $6.75 billion simply to acquire another survey company. Press Ganey brings decades of healthcare experience data, benchmarks, regulatory knowledge and embedded relationships across healthcare. Qualtrics explicitly positions the combination around creating a much larger proprietary dataset for its AI platform.
Qualtrics also announced its new XM Data & AI platform in September, with availability planned for 2027. The positioning moves noticeably beyond survey software toward an enterprise data and AI layer for understanding people and triggering action. If I were looking at Qualtrics with my finance hat on, I would say this may ultimately determine the multiple.
If investors view Qualtrics as a large survey and feedback platform with AI features, the company could struggle to earn a premium valuation. If Qualtrics becomes a proprietary customer and employee intelligence platform whose data improves enterprise AI decision-making, 3x or 4x revenue becomes easier to defend.
A move beyond that range would require stronger proof, and I think the same challenge holds true for Medallia and Sprinklr.
The future value of these companies will increasingly depend on whether AI expands the value of their data and workflows faster than it reduces the value of their existing software features.
So what happens to Qualtrics?
I do not think the most likely Qualtrics outcome is an imminent restructuring like Medallia's. Frankly, the operating profile is too strong for that to be my base case.
As a refresher, Fitch expects high-single-digit normalized revenue growth, EBITDA margins eventually reaching the high-30% range, and solid free cash flow generation. Fitch also expects debt repayment to be largely limited to mandatory amortization through 2028, which means growth and profitability are expected to do much of the work of improving leverage.
Assume the current roughly $3 billion revenue base grows around 7% annually. Revenue would reach approximately $3.7 billion in three years.
At that point:
- 2.5x revenue would imply about $9.3 billion of enterprise value.
- 3x would imply about $11.1 billion.
- 4x would imply about $14.8 billion.
- 5x would imply about $18.5 billion.
That is a much healthier picture. Even if debt declines relatively slowly, revenue growth alone reduces the debt burden as a percentage of enterprise value. So my base scenario is therefore that Silver Lake and CPP Investments do not rush an exit.
Qualtrics spends the next 3-4 years integrating Press Ganey, realizing cost savings, growing EBITDA, proving the value of the XM Data & AI platform and making the company less dependent on the market's perception of traditional experience management.
An IPO then becomes a credible path. An IPO also has one major advantage for a company this size. Qualtrics does not need to find a single buyer willing to fund a $10 billion-plus acquisition. Public investors can establish the valuation, primary capital can potentially help reduce debt and the existing owners can sell down their position over time.
A strategic acquisition is also possible. Salesforce, ServiceNow, Adobe, Oracle and other large enterprise platforms have the scale to contemplate transactions of this size, although product overlap, strategic priorities and antitrust concerns would all affect the likelihood. I am not predicting that any of those companies will buy Qualtrics.
The point is that a strategic buyer can sometimes justify a valuation that a financial buyer cannot because it can capture product, distribution, data and cost synergies.
Another private equity sale is possible as well, but it becomes more difficult when the asset already carries substantial leverage. A new sponsor needs enough room between the purchase price and a future sale price to generate an attractive return.
That room improves dramatically if Qualtrics first grows into its balance sheet.
I would therefore put my base-case Qualtrics exit somewhere around 2028 to 2030, most plausibly through an IPO or a large strategic transaction.
The company does not necessarily need to return to 6x revenue for that outcome to work. It does need to demonstrate that it deserves a meaningful premium over traditional CX software valuations.
Perhaps that's why Qualtrics's new CEO is a former equity analyst. I am sure that expertise will be helpful in the boardroom and with the investment banks vying to advise on the IPO.
There is also an interesting implication for Silver Lake. If Qualtrics reaches a $15B EV with $5B of remaining net debt, that's roughly $10B of equity value. They don't have to sell $10B of shares at the IPO. They might sell only $1B to $2B initially, use primary proceeds to reduce leverage and then monetize the remaining position through follow-ons over several years. That is one reason an IPO could be much more practical than finding another buyer for the whole company.
What this means for the CX technology market
The Medallia and Qualtrics stories are interesting individually, but I think the broader market implication matters more. A significant portion of the CX technology landscape was assembled during an era when capital was inexpensive and software valuations were much higher.
Some companies raised venture capital at aggressive valuations. Some were acquired by private equity. Others bought adjacent companies to expand from surveys into analytics, journey tools, digital experience, social listening, contact-center analytics, research and workflow automation.
The underlying assumption was that these capabilities would continue consolidating into larger experience platforms.
AI changes that assumption. We now see:
CRM companies are moving outward.
Contact-center companies are moving outward.
Analytics platforms are moving outward.
Digital experience vendors are moving outward.
AI-native companies can build capabilities that once required years of product development.
Meanwhile, buyers are looking harder at how many separate customer platforms they actually need.
Take the solar-system metaphor in the article's graphic.
Salesforce sits close to the center because it controls enormous amounts of customer data, sales workflow, service workflow and increasingly AI orchestration. Add in their recent acquisition of Listen Labs, and they now own the entire customer value loop.
ServiceNow has similar gravitational pull around enterprise workflow.
NICE and Genesys are expanding outward from the contact center.
Dozens of smaller AI-native companies are attacking specific pieces of research, feedback, analytics and customer service.
Qualtrics, Medallia, and Sprinklr remain large planets in that system.
But size alone does not guarantee orbit.
Their future depends on whether they possess assets that become more valuable as AI spreads. Things like proprietary data matter, deep enterprise integration matters, industry-specific benchmarks matter, workflow ownership matters, as does the ability to connect insight directly to operational action and proof the action had impact.
The next CX shakeout may be financial as much as technological
For technology buyers, this changes the questions worth asking.
Product capability still matters, but it is no longer sufficient to evaluate a vendor purely against a feature checklist.
Buyers should also understand the financial structure behind strategically important platforms. So if you're coming up for renewal or looking at new capabilities, I'd be asking:
Is the company producing cash?
How much debt does it carry?
Does management have room to keep investing?
Is the owner likely to seek an exit?
Does the vendor need aggressive growth simply to support its capital structure?
Could a future acquisition materially change the product roadmap?
Those questions are particularly important when selecting technology expected to remain embedded for five or ten years.
The Medallia restructuring is one example of why. The company did not disappear. Customers did not wake up to find the platform gone. But ownership changed because the capital structure no longer matched the market value of the business. That's a meaningful event for anyone buying technology on a long time horizon.
Qualtrics now represents a different, and larger test. The combined company has more than $2.9 billion in annualized revenue, powerful enterprise distribution, strong customer retention, improving profitability and one of the most interesting proprietary data positions in the CX market. It also has $6.7 billion of term debt. This analysis has shown that:
- At 1.5x revenue, the capital structure does not work.
- At roughly 2.3x, the debt is covered.
- At 3x, there is meaningful equity value.
- At 4x, the picture becomes considerably healthier.
Above that, Qualtrics begins to demonstrate that the combination of scale, data, healthcare expertise, AI and workflow deserves a valuation materially different from the rest of mature CX software. And that my fellow CXers is the bet.
Medallia has already gone through the valuation reset and emerged with new owners and a cleaner balance sheet. Sprinklr shows us what public investors are currently willing to pay when they remain skeptical about growth and differentiation. Qualtrics is trying to prove that the future of experience management is worth substantially more.
Over the next few years, we may find out whether the largest independent CX platforms can create enough new value to remain major planets in the customer technology solar system, or whether the gravitational pull of Salesforce, ServiceNow, contact-center platforms and AI-native competitors eventually redraws the market around them.
Either outcome will reshape customer experience technology buying; this time, the balance sheet may matter just as much as the product roadmap.
Sources and methodology
This analysis uses publicly available company announcements, credit-rating reports, and current public-market data.
Qualtrics revenue, debt, retention, margin and growth assumptions are primarily based on Fitch Ratings' May 20, 2026 analysis following the Press Ganey Forsta acquisition. Qualtrics and Silver Lake announcements are used for the 2023 take-private and the 2026 Press Ganey transaction.
Medallia's current revenue is not publicly disclosed. The approximately $900 million figure used here is an analytical estimate anchored by a July 2026 public statement that a Medallia executive had accountability for more than $800 million in ARR. The pre-recapitalization $2.8 billion debt figure comes from public reporting on the restructuring. Medallia has confirmed that debt was significantly reduced but has not disclosed the new balance.
Sprinklr, NICE, Five9 and DocuSign valuation comparisons use September 2026 public-market enterprise values and trailing revenue. Public-market valuations change continuously, so the multiples should be treated as point-in-time reference points rather than permanent valuation benchmarks.
Valuation scenarios in this article are illustrative analysis. They are not company guidance or investment advice.
More from Be Customer Led
If you're looking for more insight on the CX technology market, are considering going to RFP on your current technology, or need to improve the architecture of your customer technology stack, you can purchase our research by clicking here, or you can contact us directly on info@becustomerled.com to schedule an in-person meeting with the team.